
- All Insurance
- Endowment Plans
- Savings PlansNew
- Term Insurance
- Pension PlansNew
- Critical Illness Insurance
- ULIP Plan
- Group Insurance
- Protection Solutions
- Employer Employee
- Voluntary
- Affinity
- Credit Life
- Retirement Solutions
- Annuity Scheme
- Gratuity
- Leave Encashment
- Post Retirement Medical Benefits Scheme
- Superannuation
- Withdrawn Products
- NRI Plans
- Articles
- Where Do I?
- Find Customer Service
- Learn About Life Insurance
- Become a Life Insurance Advisor
- Know Our Funds
- Manage My Claim
- Know more about UPI Autopay
- Read FAQs
- Register For One ABC Id
- Download Forms
- Read Market Outlook
- Download Public Disclosures
- Disclosure of Key Performance and Financial Parameters
- Financial Calculator
- Know your Advisor
- Term Insurance
- Manage My Policy
- Her Insurance

Connect
Aditya Birla Sun Life Insurance Company Limited


Aditya Birla Sun Life Insurance Company Limited
What is an Immediate Annuity? Mechanics, payout structures, and security
 October 28, 2026
 6 mins read


Plan Smarter, Live Better!

 Table of Contents
How Much Helpful You Found This Article?

Rated by 0 reader
/ 5 ( reviews )
Not helpful
Somewhat helpfull
Helpful
Good
Best

Thank you for your feeback
Frequently asked questions
An Immediate Annuity is a contract that converts a lump sum investment into guaranteed, regular pension payments that begin almost immediately.
Immediate Annuity payouts start almost immediately after you invest your lumpsum corpus, typically within the first monthly or annual billing cycle.
Joint-Life Immediate Annuity options continue disbursing regular pension payments to the surviving spouse after the primary policyholder passes away.
Yes. Regular monthly pension disbursements from Immediate Annuities are treated as income and taxed according to your individual income tax slab rates.
Show All
Hide
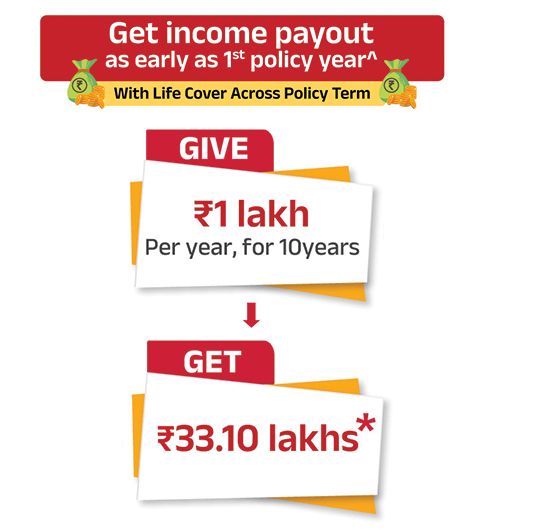
Give ₹1 lakh/ month for 5 years and Get ₹ 4.01 lakhs every year till your life1
ABSLI Guaranteed Annuity Plus
Multiple annuity options, Regular income stream.

Guaranteed# lifelong income

Top-up option for annuity
Single/Joint Life cover option
Deferred annuity option
Give :
₹ 1 lakhs/Month for 5 year¹
Get :
₹4.01 lakhs/-
 ENQUIRE NOW
Recently Added Article
Most Popular Calculator


- Claim Settlement Ratio: 98.86%* as per annual audited figures submitted to IRDAI for the period FY 25-26.
- Tax Disclaimer: Tax benefits are subject to changes in tax laws under the Income Tax Act, 1961. Consult your tax advisor for personalized guidance.
- Guarantees: #Guaranteed benefits are applicable provided all due premiums are paid on time and the policy remains in full force.
- General Disclaimer: Insurance is the subject matter of solicitation. For more details on risk factors, terms, and conditions, please read the sales brochure carefully before concluding a sale.
- IRDAI Warning: Be aware of spurious calls! IRDAI does not involve in activities like selling insurance policies, announcing bonus or investment of premiums. Public receiving such phone calls are lodged a police complaint.

