Aditya Birla Sun Life Insurance Company Limited

Is Insurance-based Retirement Plan worth buying in India? Pros, cons, and evaluation

Icon_Calender October 15, 2026
Icon-Clock5 mins read
★
4.5
Rated by 1000 readers
https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON

Plan Smarter, Live Better!

*Min 3 characters allowed
+91
*Please enter a valid 10 digit Mobile No
https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON
ICON-TICK

Thank you for your details. We will reach out to you shortly.

https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON
ICON-TICK

Currently we are facing some issue. Please try after sometime.

banner-imagemob-image
  • Icon-Index
    Table of Contents

Planning for post-career financial independence requires navigating a diverse landscape of savings vehicles, investment funds, and pension products. Among these options, Insurance-based Retirement Plan, ranging from Deferred Annuity Policies and Guaranteed Savings Plans to traditional pension schemes, play a prominent role in Indian household financial planning.

A frequent question among pre-retirees is whether allocating funds to Insurance-backed retirement products is genuinely worthwhile compared to Mutual Funds, PPF, or the National Pension System (NPS). Understanding how these plans operate, their distinct advantages, liquidity constraints, and tax implications help you determine their role in your overall retirement portfolio.

What is an Insurance-based Retirement Plan and how does it work?

An insurance-based Retirement Plan is a structured financial product designed to accumulate a post-career corpus during your working years and convert it into a regular, predictable income stream during retirement. Insurance Retirement Plans typically operate in two distinct phases:

  • Accumulation phase: During your working years, you pay regular or single premiums into the policy. These funds are systematically invested according to the plan type (guaranteed non-linked or unit-linked), allowing your capital to grow through compound interest or market participation.
  • Distribution (annuity/payout) phase: Upon reaching retirement age, the accumulated corpus or designated policy structure begins disbursing regular income payments, ensuring steady cash flow to cover post-career living expenses and eliminate longevity risk.

What are the key benefits of Insurance-based Retirement Plans?

Insurance-based Retirement Plans offer secure, predictable cash flows, built-in longevity protection, tax efficiency under Section 80C, and death benefit guarantees for family security. Integrating Insurance products into your retirement strategy provides several structural benefits:

  • Guaranteed income generation: Unlike volatile market instruments, guaranteed Non-Linked Pension Plans provide certainty regarding future payouts, helping you budget household expenses without anxiety.
  • Longevity risk mitigation: Immediate and deferred annuity options ensure that regular income disbursements continue for the remainder of your life, protecting you against outliving your savings.
  • Tax efficiency: Contributions qualify for deductions under Section 80C of the Income Tax Act, while maturity or annuity receipts enjoy specific tax exemptions depending on the policy structure.
  • Built-in life cover: Many traditional Retirement Plans include a foundational life insurance component, ensuring that surviving dependents receive financial support if an untimely demise occurs during the accumulation phase.

What are the drawbacks and limitations of Insurance Retirement Plans?

Potential drawbacks include long lock-in periods, lower liquidity during the accumulation phase, and potentially moderate returns compared to pure equity investments. Evaluating whether these plans are worth buying requires acknowledging their structural limitations:

  • Strict lock-in constraints: Retirement Insurance products are engineered for long-term holding. Premature surrenders or withdrawals often attract heavy surrender charges and disrupt compound growth.
  • Inflation risk in fixed payouts: Traditional Non-Linked Plans offer fixed nominal returns, which may face purchasing power erosion if general inflation outpaces projected yields over a 30-year retirement horizon.
  • Moderate growth profile: To provide guarantees and capital safety, traditional plans invest heavily in secure debt instruments, which typically yield lower long-term returns than aggressive equity portfolios.

How do Insurance Retirement Plans compare with NPS and Mutual Funds?

Insurance Retirement Plans prioritise capital safety and guaranteed cash flows, whereas NPS and Mutual Funds focus on market-linked growth and higher long-term wealth accumulation. Financial diversification involves understanding how different instruments complement each other:

  • National Pension System (NPS): Offers low-cost market-linked growth with mandatory annuity purchase rules upon retirement, appealing to tax-conscious investors seeking equity exposure.
  • Mutual Funds (Equity/Hybrid): Deliver superior long-term inflation-beating growth potential but carry direct market volatility risk without guaranteed income floors.
  • Insurance Retirement Plans: Provide absolute predictability, structured income certainty, and risk mitigation, making them ideal for securing foundational living expenses rather than aggressive wealth building.

How does ABSLI help?

When navigating Retirement Planning and wealth preservation, working with a trusted and transparent institution is essential. Aditya Birla Sun Life Insurance (ABSLI) offers comprehensive solutions designed to address diverse post-career planning needs. For individuals preparing for retirement, ABSLI provides specialised retirement solutions, guaranteed savings plans, and regular income products designed to build and secure long-term financial independence.

Pre-retirees should carefully review product prospectus, annuity structures, and UIN details alongside certified financial advisors before concluding any financial commitment.

How Much Helpful You Found This Article?

Rating_Star
Rated by 0 reader
/ 5 ( 0 reviews )
Not helpful
Somewhat helpfull
Helpful
Good
Best
RatingTick

Thank you for your feeback

Don’t forgot to share helpful information in your circle

Frequently asked questions

Yes, they are worthwhile if your objective is to secure a guaranteed, predictable income stream and mitigate longevity risk. However, they should be balanced with growth-oriented assets for inflation protection.

Insurance plans provide structured security, guarantees, and foundational cash flow certainty, whereas Mutual Funds offer market-linked growth potential without guaranteed payout floors.

Premiums paid toward Retirement Plans typically qualify for tax deductions under Section 80C of the Income Tax Act, subject to prevailing tax laws and statutory limits.

Retirement Plans feature strict lock-in periods designed to preserve your corpus. Early withdrawals or surrenders are restricted and can attract financial penalties or reduced surrender values.

Show All
Hide

Thank you for your details. We will reach out to you shortly.

Thanks for reaching out. Currently we are facing some issue.

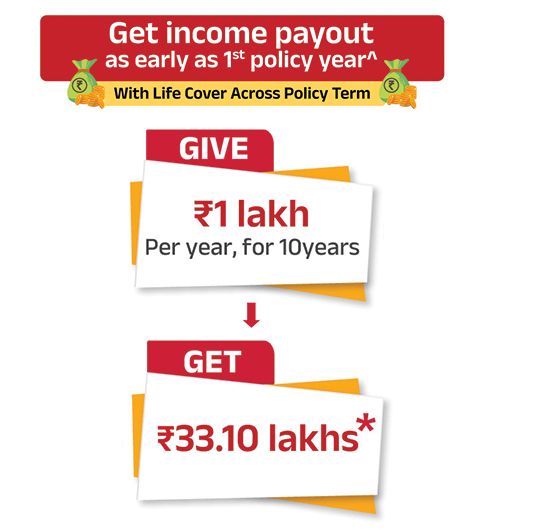
Give ₹1 lakh/ month for 5 years and Get ₹ 4.01 lakhs every year till your life1

*Min 3 characters
+91phone-icon
*Please enter a valid 10 digit Mobile No.
*This field is required.

ABSLI Guaranteed Annuity Plus

Multiple annuity options, Regular income stream.

ICON-CLICK

Guaranteed# lifelong income

Icon-Income-Benefit

Top-up option for annuity

ICON-CLICK

Single/Joint Life cover option

ICON-CLICK

Deferred annuity option

Give :
₹ 1 lakhs/Month for 5 year¹

Get :
₹4.01 lakhs/-

Claim Settlement Ratio: 98.65%* as per annual audited figures submitted to IRDAI for the period FY 25-26.

Tax Disclaimer: Tax benefits are subject to changes in tax laws under the Income Tax Act, 1961. Consult your tax advisor for personalized guidance.

Guarantees: #Guaranteed benefits are applicable provided all due premiums are paid on time and the policy remains in full force.

General Disclaimer: Insurance is the subject matter of solicitation. For more details on risk factors, terms, and conditions, please read the sales brochure carefully before concluding a sale.

IRDAI Warning: Be aware of spurious calls! IRDAI does not involve in activities like selling insurance policies, announcing bonus or investment of premiums. Public receiving such phone calls are lodged a police complaint.

whatsapp-imagewhatsapp-image