Aditya Birla Sun Life Insurance Company Limited

How to achieve financial freedom by age 40? Strategies, savings rates, and wealth accumulation

Icon_Calender October 19, 2026
Icon-Clock5 mins read
★
4.5
Rated by 1000 readers
https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON

Plan Smarter, Live Better!

*Min 3 characters allowed
+91
*Please enter a valid 10 digit Mobile No
https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON
ICON-TICK

Thank you for your details. We will reach out to you shortly.

https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON
ICON-TICK

Currently we are facing some issue. Please try after sometime.

banner-imagemob-image
  • Icon-Index
    Table of Contents

Reaching complete financial freedom by age 40 is an ambitious aspiration that requires moving far beyond conventional savings habits. While traditional financial planning assumes a career spanning up to sixty years, compressing your working timeline demands aggressive wealth accumulation, exceptionally high savings rates, and disciplined asset allocation.

Understanding the mathematics of early compounding, optimising your investment growth, eliminating liabilities, and securing sustainable passive cash flows allows you to transition from mandatory employment to absolute financial autonomy by your fourth decade.

What does financial freedom by age 40 actually include?

Financial freedom by age 40 means accumulating an investment corpus large enough to generate passive cash flows that permanently cover your annual living expenses, granting you the autonomy to choose whether or not to work. Achieving independence early in life shifts your financial focus from linear salary dependence to asset-based self-sufficiency.

  • The freedom threshold: Your accumulated capital must generate sufficient annual yields to sustain your household expenses indefinitely, adjusting for inflation across a multi-decade post-work horizon.
  • The accelerated timeline: Compressing a traditional career into 15 to 20 working years requires maximising your savings velocity from your earliest professional earnings.

How do high savings rates and compounding drive financial freedom?

Achieving independence by age 40 requires maintaining annual savings rates between 50% and 60% of income and leveraging long-term compounding to grow your corpus exponentially. The mathematics of retiring or achieving freedom by age 40 depend heavily on your savings rate:

  • The saving rate impact: Saving half your income simultaneously reduces your baseline living expenses (lowering your required corpus) and maximises the capital directed toward wealth-building assets.
  • The power of time: Starting your investment journey in your early 20s allows compound interest to generate exponential returns, turning regular monthly contributions into a multi-crore corpus before age 40.

What asset allocation strategy supports wealth building in your 30s?

A robust wealth-building portfolio for early freedom combines high-growth equity assets during your prime earning years with structured debt instruments to safeguard accumulated capital. Balancing growth and stability are essential during an accelerated accumulation phase:

  • Aggressive growth phase: Allocating significant portions of your portfolio to equity-oriented funds during your 20s and 30s captures capital market growth, helping your corpus outpace general consumer inflation.
  • Capital preservation transition: As you approach age 40, systematically rebalance your portfolio toward secure debt instruments and guaranteed income plans to protect your accumulated wealth from market corrections.

Why is eliminating personal debt critical before age 40?

Entering your fourth decade burdened with mortgages or Consumer Loans creates fixed cash flow obligations that undermine financial freedom and drain passive income streams. Carrying debt past your target independence date forces you to liquidate investments prematurely or allocate investment returns toward loan servicing instead of living expenses.

The solution: Establish an aggressive debt elimination plan during your 20s and 30s. Prioritize clearing all Home Loans, personal borrowings, and credit obligations before executing your early freedom transition.

How do guaranteed income streams secure your post-freedom cash flows?

Integrating Guaranteed Income Plans and annuity products into your financial architecture ensures your post-freedom lifestyle is supported by steady cash flows independent of market volatility. Relying solely on volatile market withdrawals introduces severe sequence-of-returns risk for early achievers.

  • Lifelong security: Buying Guaranteed Income Plans converts portions of your accumulated corpus into a reliable pension stream.
  • Longevity protection: Because achieving freedom at age 40 creates a post-work horizon spanning 40 or more years, guaranteed cash flows provide absolute security against market downturns and extended lifespans.

How does ABSLI help?

When navigating complex investment portfolios and striving to achieve early financial independence, working with a trusted and transparent institution is essential. Aditya Birla Sun Life Insurance (ABSLI) offers comprehensive solutions designed to accommodate diverse wealth creation and retirement goals. For individuals seeking foundational risk protection during working years, Term Plans like the ABSLI Super Term Plan provide robust income replacement with coverage starting from ₹1 Crore.

Policyholders and professionals should carefully review product prospectuses, fund performance statements, and UIN details alongside certified financial advisors before concluding any financial commitment.

How Much Helpful You Found This Article?

Rating_Star
Rated by 0 reader
/ 5 ( 0 reviews )
Not helpful
Somewhat helpfull
Helpful
Good
Best
RatingTick

Thank you for your feeback

Don’t forgot to share helpful information in your circle

Frequently asked questions

The primary requirement is maintaining a high annual savings rate (typically 50% to 60% of income), eliminating all personal debt, and leveraging compound growth over a 15-to-20-year career window.

Achieving financial independence by age 40 generally requires saving at least half of your income to simultaneously lower your lifestyle cost baseline and maximise your investment corpus.

You can protect your wealth by diversifying across growth assets and secure, guaranteed income instruments, ensuring your basic cash flows remain insulated from equity market volatility.

Because achieving freedom at age 40 creates a multi-decade horizon spanning 40 or more years, Guaranteed Income Plans provide steady, predictable cash flows that protect against longevity risk.

Show All
Hide

Thank you for your details. We will reach out to you shortly.

Thanks for reaching out. Currently we are facing some issue.

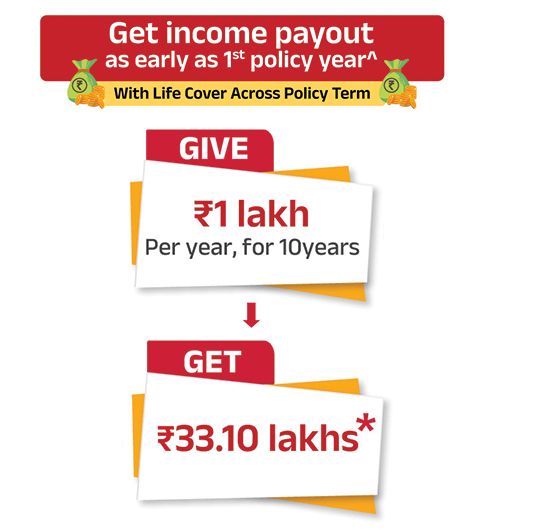
Give ₹1 lakh/ month for 5 years and Get ₹ 4.01 lakhs every year till your life1

*Min 3 characters
+91phone-icon
*Please enter a valid 10 digit Mobile No.
*This field is required.

ABSLI Guaranteed Annuity Plus

Multiple annuity options, Regular income stream.

ICON-CLICK

Guaranteed# lifelong income

Icon-Income-Benefit

Top-up option for annuity

ICON-CLICK

Single/Joint Life cover option

ICON-CLICK

Deferred annuity option

Give :
₹ 1 lakhs/Month for 5 year¹

Get :
₹4.01 lakhs/-

  • Claim Settlement Ratio: 98.65%* as per annual audited figures submitted to IRDAI for the period FY 25-26.
  • Product Classification: ABSLI Super Term Plan is a Non-Linked, Non-Participating, Individual, Pure Risk Premium Life Insurance Plan.
  • Tax Disclaimer: Tax benefits are subject to changes in tax laws under the Income Tax Act, 1961. Consult your tax advisor for personalized guidance.
  • Guarantees: #Guaranteed benefits are applicable provided all due premiums are paid on time and the policy remains in full force.
  • General Disclaimer: Insurance is the subject matter of solicitation. For more details on risk factors, terms, and conditions, please read the sales brochure carefully before concluding a sale.
  • IRDAI Warning: Be aware of spurious calls! IRDAI does not involve in activities like selling insurance policies, announcing bonus or investment of premiums. Public receiving such phone calls are lodged a police complaint.
whatsapp-imagewhatsapp-image