Aditya Birla Sun Life Insurance Company Limited

Participating vs. Non-Participating Life Insurance Policies: A guide

Icon-Calender September 21, 2026
Icon-Clock3 mins
★
4.5
Rated by 1000 readers
https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON

Plan Smarter, Live Better!

*Min 3 characters allowed
+91
*Please enter a valid 10 digit Mobile No
https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON
ICON-TICK

Thank you for your details. We will reach out to you shortly.

https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON
ICON-TICK

Currently we are facing some issue. Please try after sometime.

Read Aloud

banner-imagemob-image
  • Icon-Index
    Table of Contents

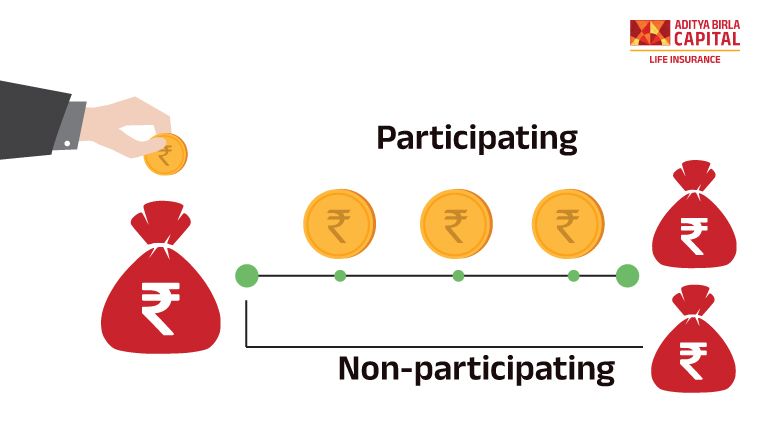
A Participating Life Insurance Policy can share a portion of an insurer’s declared surplus with eligible policyholders, generally through bonuses. A Non-Participating Policy does not share that surplus. Its benefits follow the guaranteed and non-guaranteed terms, if any, stated in the policy contract. Neither structure is automatically better. The right fit depends on how much certainty, flexibility, and bonus-linked variability you accept.

What is a Participating Life Insurance Policy?

A Participating Policy, often called a par policy, is generally a traditional Life Insurance Policy that may receive bonuses when the insurer declares them for the relevant participating fund. The policyholder “participates” in distributable surplus, not in the insurer’s ownership. Bonus eligibility, form, and timing depend on the product terms and the insurer’s declaration.

The contractual life cover and other guaranteed benefits should be distinguished from bonuses. A bonus may be added periodically, payable on death or maturity, or structured differently under the policy. A past bonus rate does not create a right to the same rate in the future. Read the benefit illustration to see which figures are guaranteed and which are illustrative.

What is a Non-Participating Life Insurance Policy?

A Non-Participating Policy, or non-par policy, does not entitle the policyholder to a share of the insurer’s declared surplus. Its payout structure is governed by the policy schedule and contract. Some benefits may be guaranteed*, while others may be conditional or non-guaranteed, depending on the product. “Non-participating” does not by itself mean that every benefit is guaranteed.

This category can suit a reader who prefers to assess benefits from the policy’s stated terms rather than rely on future bonus declarations. The essential check is not the label alone. Review the sum assured, maturity or income benefits, premium term, exclusions, surrender provisions, and any conditions attached to each payout.

What is the main difference between Participating and Non-Participating Policies?

The key distinction is surplus participation. An eligible Participating Policy can receive declared bonuses from the participating fund. A Non-Participating Policy cannot. This affects how the non-guaranteed portion of value may develop, but it does not change the need to examine the contract, benefit illustration, and premium commitment.

Comparison point

Participating policy

Non participating policy

Share in declared surplus

Eligible for policy bonuses as declared under the product terms.

No share in the insurer’s declared surplus.

Benefit pattern

May combine contractual benefits with non-guaranteed bonuses.

Follows the benefits stated in the contract. The label alone does not make every benefit guaranteed.

Visibility at purchase

Guaranteed and illustrative components should be shown separately.

Contractual payout pattern may be easier to map, subject to all conditions.

Variability

Bonus additions can vary and may not be declared.

No participating bonus variability, though other conditional features may apply.

What to verify

Bonus type, vesting, payment point, and non-guaranteed status.

Guaranteed status, payout conditions, exclusions, and surrender values.

Decision preference

May suit acceptance of bonus-linked uncertainty within a long-term insurance contract.

May suit preference for benefits defined without surplus participation.

How do bonuses work in a Participating Policy?

Bonuses arise only if they are declared in accordance with the policy terms and applicable framework. The amount may reflect the experience of the participating fund, including investment performance, claims, expenses, and other actuarial factors. A policy may refer to reversionary, terminal, or other bonus forms, but the exact terminology and payment rules are product specific. Do not treat an illustration as a promise. A sound review separates:

  • The sum assured and any other benefits explicitly stated as guaranteed*
  • Bonuses already vested or attached, where the policy terms provide for this
  • Future bonuses that are not guaranteed and may differ from illustrated values
  • Benefits that depend on continued premium payment or another stated condition

Does Non-Participating Policy mean guaranteed?

No. “Non-participating” only means that the policy does not participate in the insurer’s surplus. Whether a benefit is guaranteed depends on the wording of the product and policy contract. Look for clear labels in the benefit illustration and prospectus, then check any conditions, such as payment of all due premiums, and survival to a specified date.

Which policy type may suit your needs?

Start with the need the policy must meet, not the category label. Both types can provide life cover, and product designs within each category can differ materially. Use the following questions before deciding:

  • How much life cover is required, and for how long?
  • Can you sustain the premium across the full premium-paying term?
  • Do you want to consider potential bonus additions, knowing future bonuses are not guaranteed?
  • Which benefits are guaranteed*, and which are illustrative or conditional?
  • What happens on death, maturity, surrender, paid-up status, or a missed premium?
  • Do the payout timing and nomination arrangements match the intended family goal?

A Participating Policy may be considered when potential bonus additions are relevant and the uncertainty is understood. A Non-Participating Policy may be considered when surplus participation is unnecessary and the stated benefit design matches the goal. These are screening preferences, not substitutes for reviewing the specific product.

What should you compare before buying?

Ask for and read the sales prospectus, customised benefit illustration, and policy wording. Compare like-for-like values at the same age, premium term, policy term, sum assured, and payout option. Avoid choosing on a headline maturity figure alone.

Document or feature

What to check

Benefit illustration

Guaranteed and non-guaranteed columns, assumptions, premium outgo, and benefit timing.

Policy wording

Definitions, exclusions, premium discontinuance, paid-up value, surrender value, and claim conditions.

Policy schedule

Personal details, nominees, term, premium frequency, sum assured, and selected option.

Bonus information

Whether the bonus is declared, vested, payable, and subject to policy-specific conditions.

Free-look terms

The period and process stated in the policy for reviewing and returning it, subject to applicable deductions and rules.

Service route

Official payment channels, nomination updates, grievance process, and insurer contact details.

How can ABSLI help you compare?

ABSLI provides policy prospectus, benefit illustrations, and servicing information through its official website and authorised channels. When considering any ABSLI Policy, confirm its participating or non-participating classification, UIN, current sales material, and benefit conditions in the applicable documents. Do not rely on a category article as a substitute for the policy contract.

What is the practical takeaway?

Choose only after separating assured contractual benefits from possible future additions. A Participating Policy offers eligibility for declared surplus-linked bonuses. A Non-Participating Policy does not. Your decision should rest on adequate life cover, affordable premiums, suitable payout timing, and a clear understanding of guarantees, conditions, and surrender consequences.

How Much Helpful You Found This Article?

Rating_Star
Rated by 0 reader
/ 5 ( 0 reviews )
Not helpful
Somewhat helpfull
Helpful
Good
Best
RatingTick

Thank you for your feeback

Don’t forgot to share helpful information in your circle

Frequently asked questions

No. Future bonuses are generally not guaranteed and depend on declaration under the applicable product terms. Check whether any bonus has already vested, when it becomes payable and what happens if the policy becomes paid-up or is surrendered.

Yes. Because future bonuses are not assured, a Participating Policy may receive a lower bonus than illustrated or no bonus for a period, subject to the policy terms and the insurer’s declaration. Guaranteed contractual benefits, if any, should be assessed separately.

Usually, the classification is built into the product and cannot simply be changed within the same policy. A new purchase or another permitted option may be required. Do not surrender or replace a policy without first checking charges, surrender value, fresh underwriting, and loss of existing benefits.

Not necessarily. Premiums depend on multiple factors, including age, cover, term, underwriting, and product design. Compare the same benefit assumptions and read the benefit illustration rather than inferring price from the participating label.

Check the product classification printed in the sales prospectus, benefit illustration, and policy document. It generally states whether the policy is participating vs. non-participating and whether it is linked or non-linked. Confirm the UIN for the specific product version.

Show All
Hide

5 References

Live source article and ABSLI corporate disclosures: https://lifeinsurance.adityabirlacapital.com/articles/life-insurance/difference-between-participating-and-non-participating-policy/

Department of Financial Services: IRDAI Insurance Products Regulations 2024 and policyholder-protection regulations: https://financialservices.gov.in/act-and-policies/3485

IRDAI official website: https://irdai.gov.in/

ABSLI official website and sales literature access: https://lifeinsurance.adityabirlacapital.com/

Thank you for your details. We will reach out shortly.

Thanks for reaching out. Currently we are facing some issue.

Buy ₹1 Crore Term Insurance at Just ₹575/month*

Please enter a valid First Name.
+91phone-icon
Please enter a valid Mobile Number.
*This field is required.

ABSLI Super Term Plan

Term plan designed for salaried individual.

Icon-Illustration Insurance

3 Plan Options

Icon-Whole life cover

Health Management Service Worth ₹74000

ICON-CLICK

100% return of premium

Life Cover
₹1 crore

Premium:
₹575/month*

*Any guaranteed benefit is payable only subject to the policy terms and conditions and provided all due premiums are paid. T&C apply.

This article is for information and awareness purposes only. It does not constitute financial, investment, legal or tax advice and does not form part of an offer or recommendation. Life insurance products are subject to the terms, conditions, exclusions, limitations and underwriting requirements of the applicable policy contract. The policy document prevails in the event of any inconsistency.

Tax benefits, if any, are subject to prevailing tax laws and fulfilment of prescribed conditions. Tax laws may change. Please consult an independent tax professional for advice relevant to your circumstances.

IRDAI or its officials do not involve in activities like selling insurance policies, announcing bonus or investment of premiums. Public receiving such phone calls are requested to lodge a police complaint.

whatsapp-imagewhatsapp-image