You can grow money with Life Insurance only once cover is in place. A Term Plan protects your family with a fixed sum assured, while Savings and Unit-Linked Plans set aside part of each premium for a future benefit. The right choice depends on how much certainty you want and how much market risk you can carry. This guide explains what each plan type does, what it costs, and where the risk sits.
What is Life Insurance?
Life Insurance is a contract in which an insurer pays a sum assured or death benefit to your nominee if you die during the policy term, in return for the premiums you pay. Some plans also pay a maturity benefit or regular income if you survive, which is where the savings element comes from. Plans fall into four broad groups. A Term Plan is pure risk cover with no maturity benefit. A Non-Linked Savings Plan, such as an Endowment Plan, pairs life cover with a benefit payable on maturity or as income.
A Unit Linked Insurance Plan (ULIP) links part of the premium to market funds. A Pension Plan builds a corpus for retirement income. Every plan is also classified as Linked and Non-Linked, Participating and Non-Participating, and Individual and Group, and that classification tells you who carries the risk.
How can Life Insurance help your money grow?
Life Insurance helps money grow in three ways:
- It protects your savings from being drained by a family emergency.
- A Savings Plan sets up a defined maturity or income benefit.
- A ULIPs ties part of the premium to market funds.
Only the last carries market risk for you. The table compares the three plan types. It covers plan types only, so read each product’s prospectus for its own terms.
|
Plan type
|
Main purpose
|
Classification
|
Who carries market risk
|
|
Term Plan
|
Income replacement for your family
|
Non-Linked, pure risk
|
No fund is involved
|
|
Savings Plan
|
Defined maturity or income benefit as per policy terms
|
Non-Linked. Participating or Non-Participating
|
The insurer manages the money. Benefits follow policy terms
|
|
ULIP
|
Life cover plus a market-linked fund value
|
Linked
|
The policyholder
|
Protection comes first because a growth plan works only while the policy stays in force. A policy that lapses after a missed premium can end both the cover and the build-up, so choose a premium you can pay for the full premium payment term.
What is a Term Plan? Where does it fit?
A Term Plan is Pure Risk Life Insurance. It pays the sum assured to your nominee if you die during the policy term and pays nothing if you survive. Because no part of the premium is set aside for savings, the cover is large relative to the premium, and your goal savings are not raided in an emergency.
In a growth plan, the Term Plan is the base layer. A family with a Home Loan and school fees needs a sum assured that clears debts and funds goals. A Savings Plan or ULIP is priced to build a benefit as well as provide cover, so the premium for the same sum assured is higher.
How do Savings Plans build a defined benefit?
A Non-Linked Savings Plan pairs life cover with a maturity benefit or regular income that is set when you buy the policy, provided all due premiums are paid. The insurer manages the money, so you do not choose funds or carry daily market risk. In Participating Plans, bonuses are declared by the insurer and are not assured.
These plans suit goals with a fixed date, such as a child’s education fee or the year retirement income should start. You choose a policy term and a premium payment term, and premiums may stop before the policy ends while cover continues. For example (illustrative only), a 30-year-old could pay premiums for 10 years on a 20-year policy, and cover and benefits then continue for a further 10 years without more premiums, provided all due premiums were paid.
How does a ULIP work? What does it cost?
A Unit-Linked Insurance Plan (ULIP) is an Insurance product. After charges, part of each premium buys units in funds you choose, and the rest pays for Life Cover. The fund value moves with the Net Asset Value (NAV) of those funds, and the investment risk is borne by the policyholder. You choose from equity funds, debt funds and money market funds, or a mix. Equity Funds carry higher risk. Debt funds hold instruments such as government securities and corporate bonds.
Money Market Funds hold short-term instruments such as treasury bills and commercial paper. A fund manager manages each fund, and the policy lets you switch between funds without buying a new plan. Your premium buys units at the day’s NAV:
Units = amount allocated to the fund after charges ÷ NAV
Fund value = NAV × number of units.
Four charges reduce what stays in the fund: a premium allocation charge, deducted before units are bought; a policy administration charge, a fund management charge, and a mortality charge for the life cover, which depends on your age and the sum assured. If you die during the policy term, your nominee receives either the higher of the sum assured and the fund value, or the sum assured plus the fund value, depending on the plan.
On maturity, you receive the fund value on the maturity date. A ULIP is a long-term policy, and you cannot surrender or withdraw until the end of the fifth year.
How does the MWP Act in Insurance protect your family’s money?
Under Section 6 of the Married Women’s Property (MWP) Act, 1874, a Life Policy taken by a married man on his own life for the benefit of his wife, his children, or both becomes a trust. The proceeds stay beyond the reach of his creditors and do not form part of his estate. You must ask for MWP coverage when you apply, and the policy document must record it. A trustee, such as a family member, is named to receive the proceeds on your behalf.
For a business owner with Loans, this is what keeps the family’s protection separate from business debts. Whether MWP can be added to a particular plan depends on the insurer’s underwriting rules, so confirm it at the proposal stage.
How do you choose between protection and growth?
The most common mistake seen is a buyer who picks a plan for its maturity figure and ends up with Life Cover too small for the family’s loans and expenses. Fix the sum assured first, then ask three questions. When do you need the money? How much fall in fund value can you accept? Can you pay the premium for the full premium payment term?
If you need money on a fixed date and want defined benefits, a Non-Linked Savings Plan fits. If your horizon is long and you accept market risk, a ULIP fit. If you are unsure, a Term Plan alone is a sound base to start from. The financial calculators help you test the numbers before you decide.
How can ABSLI help?
Aditya Birla Sun Life Insurance Company Limited (ABSLI) offers plans in the categories covered above. Two examples, with their classification and life cover element:
- ABSLI Super Term Plan is a Non-Linked, Non-Participating, Individual Life Insurance. It pays the sum assured (Life Cover) to your nominee if you die during the policy term. Know more.
- ABSLI Nishchit Aayush Plan is a Non-Linked, Non-Participating, Individual Savings Plan. It combines life cover with an income benefit and a maturity benefit, as per the benefit option you choose, provided all due premiums are paid. Know more.




 October 27, 2026
 5 mins read

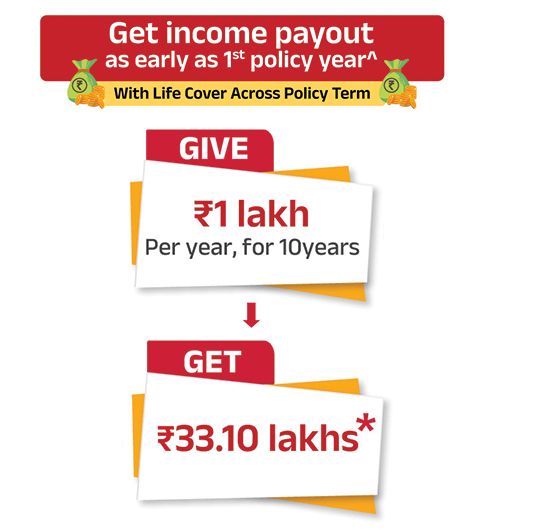


 Table of Contents


 BUY ONLINE