Choosing between a Unit-Linked Insurance Plan and an Endowment Plan comes down to one question: do you want your money to grow with the market, or do you want a fixed, guaranteed amount at maturity? Aditya Birla Sun Life Insurance (ABSLI) offers both types of plans, and each is built for a different goal. An Endowment Plan combines life cover with guaranteed savings.
A Unit Linked Insurance Plan (ULIP) combines life cover with market-linked investment. This guide compares both across returns, lock-in, flexibility and tax treatment, so you can match the plan to your goal rather than the other way around.
What is the difference between a ULIP and an Endowment Plan?
The core difference is where your money goes once the cost of the life cover is set aside. An Endowment Plan channels it into the insurer's traditional fund and pays a guaranteed lumpsum at maturity, along with bonuses if declared. A ULIP invests it in market-linked funds that you choose, such as Equity, Debt, or Balanced Funds, so the eventual payout depends on how those funds perform.
The ABSLI Vision Endowment Plus Plan is an example of an Endowment Plan built around secured savings. The ABSLI Wealth Aspire Plan is an example of a ULIP, offering a choice of market-linked funds. Both categories are explained in more depth on the Endowment Plans and ULIP Plan pages.
How do returns differ between a ULIP and an Endowment Plan at maturity?
Endowment Plans pay a pre-decided, guaranteed maturity amount, plus bonuses if the insurer declares any that year. ULIPs pay whatever your units are worth at the prevailing Net Asset Value (NAV) on your maturity date, so the exact amount is not known in advance.
For illustration only: if you hold 10,000 units in a ULIP fund and the NAV on your maturity date is Rs. 15 per unit, your fund value would work out to Rs. 1,50,000 (10,000 x Rs. 15). This is a simplified illustration to explain how unit-linked payouts are calculated. It is not a projection, promise or guarantee of actual returns, which depend on real market performance, applicable charges and the specific fund(s) chosen. This is general information only and not personalised financial advice.
What are the lock-in period and withdrawal rules?
A ULIP carries a mandatory 5-year lock-in, during which no withdrawal is permitted. After the lock-in ends, partial withdrawals may be allowed, subject to the specific plan's terms and any applicable charges. An Endowment Plan does not carry a lock-in in the same sense. It runs for its full policy term, and the life cover stays in force throughout. You can surrender an Endowment Plan early, but this is subject to a surrender value formula and possible penalties, and your life cover ends once you surrender.
How much investment flexibility do they offer?
An Endowment Plan offers limited flexibility. The insurer decides where the traditional fund is invested, and you cannot switch between investment types once the policy is issued. Some Endowment Plans offer a top-up facility to enhance the cover and benefits. A ULIP gives you the choice upfront, letting you pick from options like Equity, Debt, and Balanced Funds, and typically allows you to switch between funds during the policy term, subject to the number of free switches specified in that plan.
If your risk appetite changes, for instance if you want to move from Equity to Debt as you near a goal, a ULIP is built for that kind of adjustment. An Endowment Plan is not.
ULIPs vs. Endowment Plans: Quick comparison
|
Particulars
|
Endowment Plan
|
ULIP
|
|
Core structure
|
Insurance + guaranteed savings
|
Insurance + market-linked investment
|
|
Lock-in period
|
No statutory lock-in (has a maturity period)
|
Mandatory 5 years
|
|
Investment tracking
|
No day-to-day fund visibility
|
Fund value and NAV visible to the policyholder
|
|
Fund switching
|
Not applicable
|
Permitted, subject to plan terms
|
|
Maturity payout
|
Guaranteed sum plus bonuses, if declared
|
Depends on fund performance and NAV on the maturity date
|
|
Market risk
|
Protected from day-to-day market movements
|
Bears market risk on the invested portion
|
|
Premium
|
Typically, lower for the same sum assured [VERIFY against UIN]
|
Typically higher, as part funds the investment
|
|
Tax treatment (general)
|
80C and 10(10D)*, subject to the premium not exceeding 10% of sum assured
|
80C and 10(10D)*, subject to annual premium not exceeding Rs. 2.5 lakh
|
*Tax treatment is general information based on prevailing income tax law and is subject to conditions; see the tax section below and consult a tax professional for your specific situation.
What are the tax benefits of ULIPs and Endowment Plans?
Both ULIPs and Endowment Plans qualify for a deduction on premiums paid under Section 80C of the Income Tax Act, 1961, up to the overall Section 80C limit. Both also offer tax-free maturity and death benefits under Section 10(10D), but this exemption comes with conditions that are often left out of simple comparisons. For ULIPs issued on or after 1 February 2021, the Section 10(10D) exemption applies only if your total annual premium across all ULIPs in that policy year does not exceed Rs. 2.5 lakh; above that, maturity proceeds may be taxed as capital gains.
For Endowment and other Traditional Life Insurance Plans issued on or after 1 April 2012, the premium must not exceed 10% of the sum assured (15% in specified disability or critical-illness cases) for the maturity benefit to stay tax-free. This is general information based on prevailing tax law and not personalised tax advice; your actual tax treatment depends on your full policy and income details, so it is worth checking with a tax professional before you decide.
Which one should you choose?
There is no universally "better" option. It depends on what you are optimising for. If a fixed, predictable amount at maturity matters more to you than the possibility of higher growth, and you are not comfortable with market swings, an Endowment Plan fits that goal. If you have a longer investment horizon, some appetite for market risk, and want the ability to adjust your fund mix as your circumstances change, a ULIP is built for that.
Many households use both: an Endowment Plan for a guaranteed, protected portion of their savings, and a ULIP for a market-linked portion aimed at long-term wealth creation. Whichever you pick, check the fund options, charges, and switch rules against the current UIN-approved product brochure before you buy, since these vary by plan.






 September 4, 2026
 5 mins read




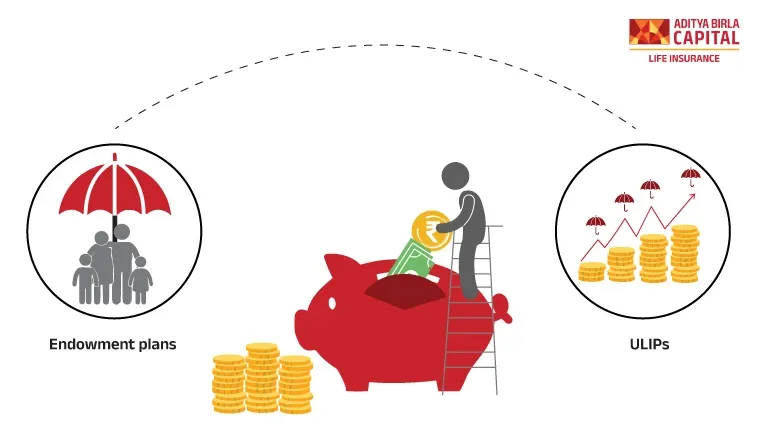
 Table of Contents


 BUY ONLINE