Aditya Birla Sun Life Insurance Company Limited

How to switch from Group Insurance to Individual Term Insurance?

Icon_Calender September 17, 2026
Icon-Clock10 mins
★
4.5
Rated by 1000 readers
https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON

Plan Smarter, Live Better!

*Min 3 characters allowed
+91
*Please enter a valid 10 digit Mobile No
https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON
ICON-TICK

Thank you for your details. We will reach out to you shortly.

https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON
ICON-TICK

Currently we are facing some issue. Please try after sometime.

Read Aloud

banner-imagemob-image
  • Icon-Index
    Table of Contents

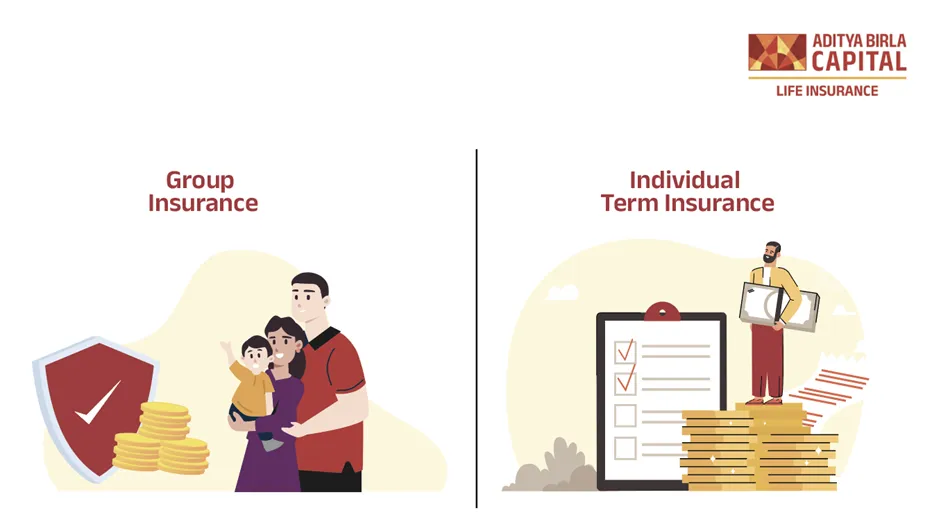
The biggest difference is who owns and controls the policy. Group Term Insurance is provided as part of an employer or group arrangement, while Individual Term Insurance is bought and owned by you. Group cover is generally linked to your membership in the group, whereas an individual policy continues independently of your employment, subject to its terms and applicable premiums.

How to switch between the Insurance?

Moving from Group to Individual Term Insurance is not necessarily a direct transfer of your existing policy. The first step is to check what happens to your group cover when you leave your employer and whether the group policy offers a conversion option. If a conversion facility is available, check the terms, eligibility, and process with your employer or insurer. If it is not available, you can explore a separate Individual Term Plan based on your financial responsibilities and protection needs.

What to check before you switch from Group Term Insurance to Individual Term Insurance?

Before making the move, review:

  • When your group cover ends
  • Whether a conversion option is available
  • How much cover you currently have
  • How much cover your family may need
  • Whether you already have individual life insurance

This is important because your group cover is linked to your employment, while an Individual Term Plan is personally owned. Your job may change, but your financial responsibilities may continue.

What happens to your Group Term Insurance when you change jobs?

Group Term Insurance is generally linked to your employment or membership of the group. So, when you leave the employer, your eligibility for that group cover may end according to the policy terms. This can create a gap if your family is relying on that cover. For example, you may have started with group insurance when you had fewer financial responsibilities. Years later, you may have a Home Loan, children, or dependent parents. The cover provided by your employer may no longer be the only protection you want to rely on.

Should you buy Individual Term Insurance before leaving your job?

If your family depends on your income, it may be worth arranging individual life cover before your group cover ends. An Individual Term Plan can give you personal ownership of the cover, subject to the policy terms. Your employment can change, but your policy does not depend on staying with the same employer. This can be particularly relevant if you have:

  • A spouse or children, dependent on your income
  • Outstanding Loans
  • Dependent parents
  • Long-term financial commitments
  • Financial goals that depend on your future income

Can you convert Group Term Insurance into Individual Term Insurance?

Not necessarily. Some Group Insurance arrangements may provide a conversion option, but this depends on the specific group policy and its terms. Check with your employer, group policy administrator or insurer to understand whether such an option is available and what conditions apply. If conversion is not available, you can explore Individual Term Insurance.

It is therefore better to think of this as moving from employer-linked protection to personally owned protection, rather than assuming that your existing group policy can always be converted.

How much Individual Term Insurance should you consider after leaving a Group Plan?

Do not simply replace your group cover with the same amount. Your employer-provided cover may have been designed as an employee benefit. Your individual cover should instead reflect your personal financial responsibilities. Consider:

  • Your dependents
  • Outstanding Loans
  • Children's education
  • Regular household expenses
  • Long-term financial goals
  • Existing savings and assets
  • Other life insurance policies you already hold

The objective is to understand the financial gap your family could face if your income were no longer available.

What happens when you buy Individual Term Insurance?

Unlike an employer-provided group arrangement, an Individual Plan is assessed based on the individual's details and the insurer's underwriting process. Depending on the plan and application, factors such as age, health, lifestyle, occupation, income, and the amount of cover sought may be relevant. This means you should not wait until your group cover has already ended before starting the process. If you are planning a job change, give yourself enough time to understand your existing cover and arrange any additional individual protection you may need.

Do you need to stop your Group Insurance before buying Individual Term Insurance?

No. You do not necessarily have to choose between the two while you are still covered under your employer's group policy. Having group cover through your employer and separately holding an individual term insurance policy can mean that you have both forms of protection while you remain eligible for the group cover. The important point is to understand that they serve different purposes. Your group cover is connected to your employment, while your individual policy is personally owned.

What should you check for in your Group Term Insurance before leaving your employer?

A job change is a good time to review your Insurance rather than treating it as an HR formality. Before you leave, check:

  • How much group cover do I currently have?
  • When does my group cover end?
  • Does my group policy offer a conversion option?
  • What financial responsibilities do I currently have?
  • Do I already have individual life cover?
  • Would my family be financially affected if my income stopped?
  • Do I need additional individual cover?

This gives you a clearer picture of whether you are adequately protected after the job change.

How can ABSLI help you move towards Individual Term Insurance?

If you are looking to build protection that is not linked to your employer, you can explore ABSLI Term Insurance Plans based on your individual protection needs. The ABSLI Term Insurance calculator can help you assess your potential cover and premium based on relevant details.

For salaried professionals, the ABSLI Salaried Term Plan is an option to consider for individual life cover. Read the policy document and sales literature carefully before making a decision.

How Much Helpful You Found This Article?

Rating_Star
Rated by 0 reader
/ 5 ( 0 reviews )
Not helpful
Somewhat helpfull
Helpful
Good
Best
RatingTick

Thank you for your feeback

Don’t forgot to share helpful information in your circle

Frequently asked questions

It depends on the terms of the group policy. Since group cover is generally linked to group membership, your coverage may end when you leave the organisation. Check the applicable policy terms and any conversion facility before leaving.

Yes. Having employer-provided group cover does not necessarily prevent you from buying an Individual Term Plan, subject to the insurer's eligibility and underwriting requirements.

They serve different purposes. Group Term Insurance is linked to your group membership, while Individual Plans are personally bought and owned. The appropriate choice depends on your financial responsibilities and existing protection.

You can assess the new employer's group cover alongside your existing individual cover and overall financial responsibilities. A new group policy does not automatically replace the need for personally owned protection.

Not necessarily. The amount provided under an employer's group policy may not reflect your current income, liabilities, dependents, and long-term goals. Assess your individual protection needs separately.

Show All
Hide

Thank you for your details. We will reach out shortly.

Thanks for reaching out. Currently we are facing some issue.

Buy ₹1 Crore Term Insurance at Just ₹575/month*

Please enter a valid First Name.
+91phone-icon
Please enter a valid Mobile Number.
*This field is required.

ABSLI Super Term Plan

Term plan designed for salaried individual.

Icon-Illustration Insurance

3 Plan Options

Icon-Whole life cover

Health Management Service Worth ₹74000

ICON-CLICK

100% return of premium

Life Cover
₹1 crore

Premium:
₹575/month*

This article is for informational purposes only. The information provided is subject to change and should not be considered as financial, legal, medical or tax advice. Insurance is the subject matter of solicitation. Please refer to the policy document, prospectus and terms and conditions for complete details. Tax benefits are subject to change as per prevailing tax laws (Income-tax Act, 2025). Please consult a qualified tax advisor.

BEWARE OF SPURIOUS PHONE CALLS AND FICTITIOUS / FRAUDULENT OFFERS. IRDAI or its officials do not involve in activities like selling insurance policies, announcing bonus or investment of premiums. Public receiving such phone calls are requested to lodge a police complaint.

Tax benefits are subject to change as per prevailing tax laws. Please consult a qualified tax advisor.

whatsapp-imagewhatsapp-image