
- All Insurance
- Endowment Plans
- Savings PlansNew
- Term Insurance
- Pension PlansNew
- Critical Illness Insurance
- ULIP Plan
- Group Insurance
- Protection Solutions
- Employer Employee
- Voluntary
- Affinity
- Credit Life
- Retirement Solutions
- Annuity Scheme
- Gratuity
- Leave Encashment
- Post Retirement Medical Benefits Scheme
- Superannuation
- Withdrawn Products
- NRI Plans
- Articles
- Where Do I?
- Find Customer Service
- Learn About Life Insurance
- Become a Life Insurance Advisor
- Know Our Funds
- Manage My Claim
- Know more about UPI Autopay
- Read FAQs
- Register For One ABC Id
- Download Forms
- Read Market Outlook
- Download Public Disclosures
- Disclosure of Key Performance and Financial Parameters
- Financial Calculator
- Know your Advisor
- Term Insurance
- Manage My Policy
- Her Insurance

Connect
Aditya Birla Sun Life Insurance Company Limited


Aditya Birla Sun Life Insurance Company Limited
How much should you invest each month?
 October 27, 2026
 5 mins read


Plan Smarter, Live Better!

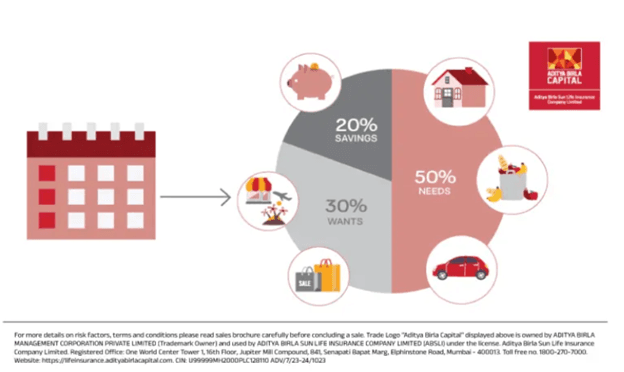
 Table of Contents
How Much Helpful You Found This Article?

Rated by 0 reader
/ 5 ( reviews )
Not helpful
Somewhat helpfull
Helpful
Good
Best

Thank you for your feeback
Frequently asked questions
They are part of your long-term savings, so include them when you look at your overall picture. However, they are usually set aside for retirement and are not easy to use for nearer goals. Many people treat them as their retirement base and still save separately from take-home pay for goals such as a home, a car, or a child's education, so their plans do not rely on a single source.
Decide before the money arrives, so it is not absorbed by everyday spending. A sensible order is to rebuild your emergency fund, clear any high-interest debt, and then add the rest to your goals. Keeping a small share of something you enjoy makes the plan easier to stick to. A windfall should add to your regular monthly saving, not replace it.
Starting small is better than waiting. A modest monthly amount builds the habit, gives your money more time to grow and is easy to increase as your income rises. Waiting until you can afford a larger sum often means losing years you cannot get back. Set an amount you can sustain comfortably now, and plan to review it with your next pay rise.
Show All
Hide
Get immediate income payout after 1 day of policy issuance^
ABSLI Nishchit Aayush Plan

Guaranteed# Income
Life Cover across policy term
Lumpsum Benefit at policy maturity.
Get:
₹39.22 lakhs~
Pay:
₹1 Lakh/year for 12 Years
 BUY ONLINE
Recently Added Article
Most Popular Calculator


BEWARE OF SPURIOUS PHONE CALLS AND FICTITIOUS / FRAUDULENT OFFERS. IRDAI or its officials do not involve in activities like selling insurance policies, announcing bonus or investment of premiums. Public receiving such phone calls are requested to lodge a police complaint.
This article is for general information only and does not constitute financial advice. Please consider your own circumstances or consult a qualified financial advisor before making decisions.

