Aditya Birla Sun Life Insurance Company Limited

Is ULIP a smart investment choice in 2026?

Icon-Calender September 8, 2026
Icon-Clock5 mins read
★
4.5
Rated by 1000 readers
https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON

Plan Smarter, Live Better!

*Min 3 characters allowed
+91
*Please enter a valid 10 digit Mobile No
https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON
ICON-TICK

Thank you for your details. We will reach out to you shortly.

https://lifeinsurance.adityabirlacapital.comnullCLOSE-BUTTON
ICON-TICK

Currently we are facing some issue. Please try after sometime.

banner-imagemob-image
  • Icon-Index
    Table of Contents

A Unit Linked Insurance Plan (ULIP) may suit a long-term goal when you need life cover, can stay invested beyond the five-year lock-in, understand market risk, and are comfortable reviewing fund allocation over time. It is not automatically suitable for everyone. Your decision should follow your protection need, time horizon, risk capacity, cash-flow stability and the policy’s charges and conditions.

What exactly does a ULIP combine?

A ULIP combines Life Insurance with market-linked fund allocation in one policy. Part of each premium supports Insurance and applicable charges. The balance buys units in the fund or funds you select. The policy’s fund value changes with the net asset value (NAV) of those units, so it can rise or fall. Available fund categories commonly include Equity, Debt, Balanced, or managed options. Names, asset mix and risk levels differ by product.

The Customer Information Sheet, sales prospectus, and policy document should show the available funds, benefit structure, charges, exclusions, and switching rules.

When can a ULIP fit a long-term financial goal?

A ULIP is more likely to fit when your goal is several years away, your income can support the chosen premium term, and you accept that the final fund value is uncertain. The five-year lock-in is a minimum regulatory feature, not a promise that five years is an adequate horizon for every goal.

  • You have a clearly estimated goal amount and date, such as education, retirement, or a future home contribution.
  • You separately assess how much life cover your dependents need instead of treating the ULIP’s default cover as automatically sufficient.
  • You can continue premiums through ordinary income disruptions and maintain a separate emergency reserve.
  • You understand that fund performance can be negative over some periods and that staying invested does not guarantee a gain.
  • You are willing to review allocation periodically without reacting to every short-term market move.

When might a ULIP be unsuitable?

It may be unsuitable when you may need the money within five years, cannot tolerate fluctuations, require a predictable maturity amount, or may struggle to pay premiums. It may also be a poor fit if you do not understand the charges or if the life cover does not meet your family’s protection requirement.

Do not rely on a sales illustration alone. Ask what happens if you stop premiums, surrender early, make a partial withdrawal, or leave the fund allocation unchanged. Benefit illustrations use prescribed assumptions. They are not forecasts of the amount you will receive.

How should you assess risk and choose funds?

Choose funds using your goal horizon, capacity to absorb loss, and required asset mix, not recent returns. Equity Funds can fluctuate more. Debt Funds can also face interest-rate and credit risks. A Balanced Fund spreads exposure but does not remove market risk. Switching may help restore your intended allocation or reduce risk as a goal approaches.

The number of free switches, any later charge and the process vary by plan. Frequent switching or trying to predict short-term market movements can undermine a disciplined plan. Check the policy document before acting.

Which ULIP charges should you check?

Review every applicable charge because charges reduce the premium allocated to funds or the fund value. The exact structure is product-specific and may change across policy years only as permitted by the contract and regulation.

  • Premium allocation charge, if applicable, deducted before units are allocated.
  • Policy administration charge for policy servicing and administration.
  • Mortality charge for the Life Insurance risk cover, usually affected by age, cover, and fund value under the policy formula.
  • Fund management charge reflected in the NAV of the chosen fund.
  • Switching, partial-withdrawal, or discontinuance charges, where the policy permits them.

Compare the charge schedule across the full intended holding period. Read the Customer Information Sheet and sales prospectus, and ask for an explanation of any item you do not understand.

What does the five-year lock-in mean?

A ULIP does not provide liquidity during the first five policy years. You cannot ordinarily withdraw the money invested, wholly or partly, during that period. If premiums stop or the policy is surrendered during the lock-in, discontinuance provisions apply and payment is generally deferred until the lock-in ends, subject to policy terms.

Partial withdrawals may be available after five years, subject to eligibility, limits, and charges. A withdrawal reduces the goal corpus and may affect benefits under the policy. Use it only after checking the effect on life cover and the amount needed for your goal.

How does life cover work in a ULIP?

A ULIP includes a death benefit, but the calculation is not identical across products. Depending on the policy, the benefit may reference the sum assured, fund value, premiums paid, or another formula, with applicable deductions and conditions. Never assume that every ULIP pays the higher of the sum assured and fund value.

Estimate your family’s protection need independently, considering income replacement, liabilities, dependents, and existing cover. Then confirm whether the policy’s death benefit is adequate and how partial withdrawals or age-related mortality charges may affect it.

What are the ULIP tax rules to check in 2026?

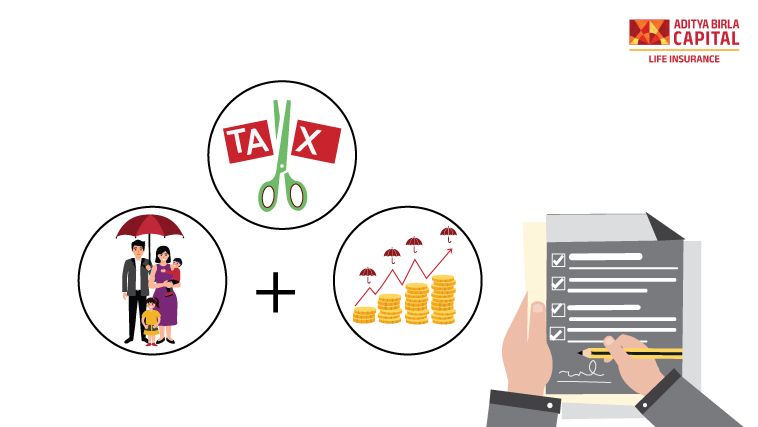
Tax treatment is conditional, not automatic. An eligible premium deduction depends on the applicable tax law, statutory limits, policy conditions, and the tax regime you use. Under the Income Tax Act, 1961, Section 80C benefits are generally relevant to the old tax regime and sit within the overall statutory limit, subject to conditions.

For ULIPs issued on or after 1 February 2021, maturity exemption under Section 10(10D) is subject to conditions including an aggregate annual-premium threshold of ₹2.5 lakh across applicable ULIPs. Where the conditions are not met, gains may be taxable under the relevant capital-gains provisions. Death proceeds are treated separately under Section 10(10D), subject to law. Obtain current advice for your circumstances.

What should you check before buying?

Use the product documents to verify suitability. A useful review should cover the following points before you sign or pay:

  • Goal date and required amount, with an allowance for inflation.
  • Premium amount, payment frequency, payment term, and ability to continue.
  • Death-benefit formula and whether the cover meets your protection need.
  • Fund objectives, risk classifications, and your intended asset allocation.
  • All charges, surrender, and discontinuance rules, switching limits and partial-withdrawal conditions.
  • Nomination details, exclusions, claim process, grievance route, and the free-look terms stated in the policy.
  • The two benefit illustrations provided at the prescribed assumed rates, understood as illustrations rather than assured returns.

How can ABSLI help?

Aditya Birla Sun Life Insurance Company Limited (ABSLI) offers Unit-Linked individual Life Insurance products and publishes product documents, fund information and policy-servicing resources. If you are considering an ABSLI ULIP, use the relevant sales prospectus, benefit illustration, Customer Information Sheet, and policy document to verify the exact benefits, charges, risks, and conditions.

What is the practical takeaway?

A ULIP can be considered for a long-term goal when its Insurance benefit, fund choices, charges, lock-in, and premium commitment match your needs. The word “smart” should never replace a suitability assessment. Start with your family’s protection gap and goal horizon, then decide whether you can accept market-linked outcomes and the policy’s liquidity limits.

How Much Helpful You Found This Article?

Rating_Star
Rated by 0 reader
/ 5 ( 0 reviews )
Not helpful
Somewhat helpfull
Helpful
Good
Best
RatingTick

Thank you for your feeback

Don’t forgot to share helpful information in your circle

Frequently asked questions

No. ULIP returns are linked to the performance of the selected funds and are subject to market risk. NAV can increase or decrease, and past performance does not indicate future performance. Only a benefit expressly identified as guaranteed in the policy document can be treated as such, subject to its stated conditions.

ULIPs do not offer liquidity during the first five policy years. Partial withdrawals are generally available only after the lock-in, subject to the policy’s eligibility rules, limits and charges. Early discontinuance or surrender follows separate provisions, and payment is generally made after the lock-in ends.

Many ULIPs permit fund switching, but the available funds, number of free switches, any charge, and cut-off rules are plan-specific. Use switches to support a considered asset-allocation approach, not as a promise of avoiding losses. Refer to the policy document before requesting a switch.

No. Exemption depends on the issue date and conditions under the prevailing tax law. For ULIPs issued on or after 1 February 2021, the aggregate annual-premium threshold of ₹2.5 lakh across applicable ULIPs is one important condition for Section 10(10D) maturity exemption. Consult a qualified tax adviser.

The result depends on when premiums stop and the policy terms. During the lock-in, the fund value may move to a discontinued-policy fund after applicable charges, with proceeds payable after the lock-in. After the lock-in, reduced paid-up, revival, surrender, or other options may apply. Check your policy before stopping.

Show All
Hide

To learn more, click here

Also read

References

  • Insurance Regulatory and Development Authority of India, Master Circular on Life Insurance Products, 2024 and applicable linked-product requirements: https://irdai.gov.in/
  • Income Tax Department, Income Tax Act, 1961, Sections 80C and 10(10D), as amended: https://www.incometax.gov.in/
  • Aditya Birla Sun Life Insurance, source page and company/footer information, accessed 7 September 2026: https://lifeinsurance.adityabirlacapital.com/articles/wealth-insurance/ulip-is-a-smart-choice-of-investment/
  • Aditya Birla Sun Life Insurance, ULIP information pages cited under “Also read”, accessed 7 September 2026.

Thank you for your details. We will reach out shortly.

Thanks for reaching out. Currently we are facing some issue.

Give ₹558/month and Get ₹1 crore term insurance*

Min 3 characters
+91phone-icon
Please Enter a valid 10 digit Mobile No.
*This field is required.

ABSLI Salaried Term Plan

Exclusively For Salaried Individuals

ICON-CLICK

4 Plan Options

ICON-CLICK

Life Cover upto 75 years

ICON-CLICK

Optional Accelerated Critical Illness benefit

ICON-CLICK

Inbuilt Terminal Illness Benefit

Life Cover
₹1 crore

Premium:
₹558/month*

Unit Linked Insurance Products do not offer any liquidity during the first five years of the contract. Policyholders will not be able to surrender or withdraw the monies invested in Unit Linked Insurance Products completely or partially till the end of the fifth year.

Unit Linked Insurance Products are different from traditional insurance products and are subject to market risks. The premium paid in Unit Linked Insurance Policies is subject to investment risks associated with capital markets, and the NAVs of the units may go up or down based on the performance of the fund and factors influencing the capital market. The policyholder is responsible for his or her decisions.

The names of the company, product, investment options or funds do not indicate their quality or future returns. Please know the associated risks and applicable charges from the insurance agent or intermediary, or from the policy document issued by the insurer.

This article is for general information and education only. It does not constitute personalised insurance, investment, legal or tax advice. Policy benefits, exclusions, charges, fund options and conditions are governed by the applicable policy contract. Read the sales prospectus and policy document carefully before concluding the sale.

Tax benefits are subject to provisions of the prevailing tax laws, fulfilment of prescribed conditions and the tax regime selected. Tax laws are subject to change. Please consult a qualified tax professional for advice relevant to your circumstances.

whatsapp-imagewhatsapp-image