


- All Insurance
- Endowment Plans
- Savings PlansNew
- Term Insurance
- Pension PlansNew
- Critical Illness Insurance
- ULIP Plan
- Group Insurance
- Protection Solutions
- Employer Employee
- Voluntary
- Affinity
- Credit Life
- Retirement Solutions
- Annuity Scheme
- Gratuity
- Leave Encashment
- Post Retirement Medical Benefits Scheme
- Superannuation
- Withdrawn Products
- NRI Plans
- Articles
- Where Do I?
- Find Customer Service
- Learn About Life Insurance
- Become a Life Insurance Advisor
- Know Our Funds
- Manage My Claim
- Know more about UPI Autopay
- Read FAQs
- Register For One ABC Id
- Download Forms
- Read Market Outlook
- Download Public Disclosures
- Disclosure of Key Performance and Financial Parameters
- Financial Calculator
- Know your Advisor
- Term Insurance
- Manage My Policy
- Her Insurance
Aditya Birla Sun Life Insurance Company Limited



Aditya Birla Sun Life Insurance Company Limited
Outlook for the Month of November’26
Economy Review
The key events in the month were –
- Domestic Factors –
a) RBI – The RBI MPC unanimously hiked the policy repo rate by 25bps to 5.5% and changed its stance to calibrated tightening.
b) IIP – IIP growth in September’26 moderated to 6.7% from 7.8% last month with manufacturing at 7.6%, electricity production growth at 11.2%, water, sewage and waste at 5.8% and mining at -6.2%.
c) Trade Deficit – Goods deficit widened by $ 3.4bn to $ 30.2bn in September’26, driven primarily by a sharp increase in oil and electronics deficit.
- Global Factors –
a) FOMC – FOMC kept interest rates unchanged at 3.75-4%, in line with market expectations.
b) West Asia Conflict – The West Asia crisis continue with no resolution in sight and the Strait of Hormuz continues to remain shut.
c) Crude Oil – Brent crude oil prices continue to remain elevated at above $100/bbl.
d) Precious Metals – Gold and silver prices declined by 7% and 19% in the month of October’26.
Domestic Macro Economic Data
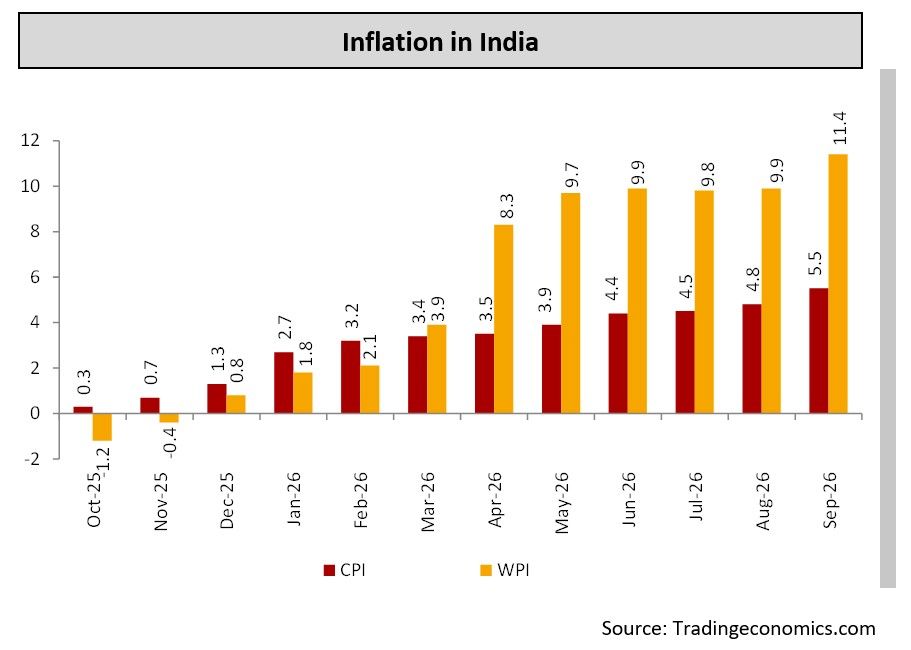
Inflation – India’s CPI inflation surged to 5.5% in September’26 vs 4.8% in August’26 due to sharp spike in food inflation. India’s WPI inflation was at a 4 year high at 11.4% in September’26, as food, fuel and manufactured products all have contributed to the elevated inflation print.
Outlook for Equities
Nifty inched by 1.9% in the month of October’26. Mid-cap and Small-cap indices underperformed the large cap correcting by 3.4% and 4.1% respectively. Global markets turned risk-off late in the month as concerns about AI capex and expectations of a Fed rate hike weighed on investor sentiment. Indian equity markets remains under pressure on persistent uncertainty over the US-Iran war and high crude oil prices. Primary market activity remained strong with 13 IPOs raising US$4.7bn during October, with JIO being the largest IPO.
Brent crude oil prices continue to remain elevated at above $100/bbl. Both the Fed and Bank of Japan kept policy rates unchanged in October’26. The RBI MPC unanimously hiked the policy repo rate by 25bps to 5.5% and changed its stance to calibrated tightening. FIIs sold $4.1bn worth of Indian equities whereas DIIs bought $5.6bn of equities during the month of October’26.
Indian markets stand at an ideal inflexion point, backed by strong economic indicators, correction in crude oil prices and nominal GDP growth of 11-12%. On the back of which Indian corporate earnings are well-positioned to deliver a 13-15% CAGR from FY26-28. Nifty is currently trading at ~17x FY28e P/E, below its long term average. We expect Nifty earnings to grow at 13-15% CAGR over FY26-28. Investors can continue to invest in equities from a medium to long-term perspective.
Outlook for Debt
RBI MPC in October’26 unanimously hiked the policy repo rate by 25 bps to 5.5% while shifting its policy stance to ‘calibrated tightening’ from ‘neutral’ by a 4-2 majority. Both growth and inflation forecasts were revised upward. MPC delivered a more hawkish-than-expected outcome, reflected in a surprise stance shift, upward revisions to inflation and growth estimates and a re-emphasis on an elevated inflation of 5.8% over the next three quarters. In minutes all MPC members noted that diffusion indices indicate the weighed share of items in the CPI basket experiencing inflation over 4-6% has increased notably. While price pressures emanate from high global fuel and commodity prices and El-Nino-led weaker monsoon, a larger pass-through of input costs to output prices may materialize. Thus, a pre-emptive course of action through rate hike is preferred over a wait-and-watch approach. The minutes highlight the MPC’s intent to maintain price stability amid rising inflation pressures.
Banking system liquidity swung to near-neutral and then small surplus from a record surplus much faster than expected through RBI's FX intervention, its targeted FX and liquidity absorption measures, festive-season currency demand and muted government spending. RBI has done liquidity infusion measures as well in order to keep system liquidity in balance. September’26 CPI inflation rose to 5.5% yoy, food inflation was driven by spices, fruits and vegetables, meat and fish and sugar. Core inflation was somewhat higher at 4.3% yoy. WPI inflation for September’26 was at 11.4% yoy, driven by high fuel and power inflation. IIP growth in September’26 was at 6.7% being led by electricity production growth. In terms of the use-based classification, growth was led by intermediate goods and capital goods.
FOMC kept the Fed funds rate unchanged in October’26 at 3.75-4%, in line with market expectations with a 10-2 majority. The FOMC stated that inflation remains elevated and that "the accumulation of more information will help the Committee determine the policy stance appropriate to ensure a timely return of inflation to the Committee's 2 percent goal.” The European Central Bank kept policy rates unchanged in the October’26 policy in line with market expectations and Bank of Japan kept their benchmark policy rate unchanged at 1.25%, with an 8-1 majority. US yields declined during the month towards 4.91%, over 40 bps lower than their immediate peak and lower by 37 bps during the month. Market expects FOMC to hike rates by 25 bps in December’26 as also safe haven demand has led treasuries off their recent highs.
In the near term, markets will watch for future expectations on rate action by RBI as USD INR currency movements have increased chatter of inter- meeting rate action. Market will also watch for further developments on liquidity measures as from substantial surplus banking system liquidity has moved towards balance. CPI inflation data will be closely watched as expectations of reaching RBI threshold on CPI during the current quarter have gained pace. In the global markets US mid-term elections results and their aftermath, labour market data as well as FOMC members speeches will be watched. Market pricing of future FED action and CPI data in global economies will also be tracked. 10-year Gsec closed at 7.41% on 30th October’6 higher by 23 bps during the month. 10-year Gsec yield in the near term is likely to be in a range of 7.20%-7.50%. Spread of 10-year Gsec with corporate bond is near 70 bps and is likely to be in a range of 65-75 bps.

